Oil & Gas IDCs: The Tax Code’s Most Aggressive Deduction, Honestly Explained
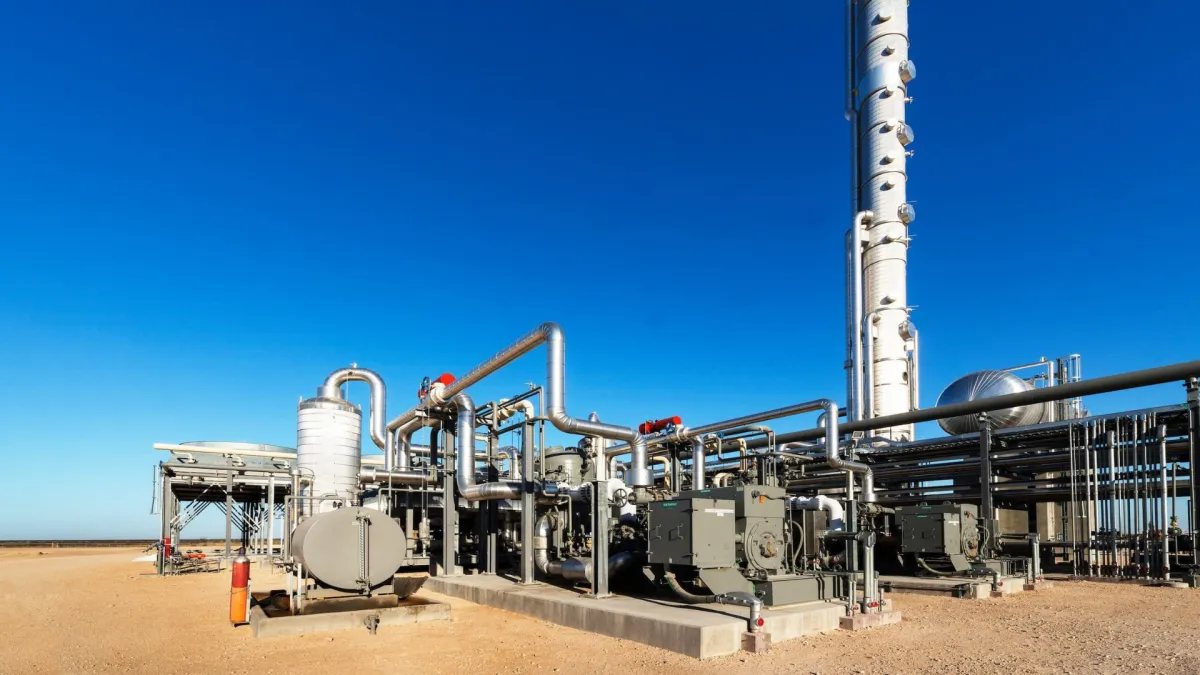
Congress has favored domestic energy drilling in the tax code for a century, and the intangible drilling cost deduction is the sharpest expression of that policy: a large share of a drilling investment potentially deductible in the year it’s made. It is also the strategy where the gap between the tax pitch and the underlying investment is widest — which is exactly why it deserves the unvarnished treatment.
What IDCs are
Intangible drilling costs are the expenses of drilling a well that have no salvage value — labor, site preparation, drilling fluids, fuel, engineering, and related services — typically a substantial majority of a well’s total cost. For qualifying investments structured with general-partner-style interests, the tax code permits these costs to be deducted currently rather than capitalized, which is what produces the headline: a first-year deduction that can offset a meaningful portion of the amount invested, in some structures against ordinary income.
The part the tax math skips
Here is the sentence every IDC brochure should open with: the deduction only converts a loss into a smaller loss unless the wells produce. Drilling involves geological risk — wells can underperform projections or fail entirely — plus commodity price exposure for years afterward, and operator execution risk on top of both. A deduction at your marginal rate returns a fraction of each dollar invested; the rest is riding on hydrocarbons actually coming out of the ground at prices that justify the drilling. The tax benefit lowers the breakeven. It does not repeal geology.
1031 Exchanges: A Powerful Tax-Deferral Strategy
The complete 14-page primer on like-kind exchanges — rules, deadlines, and strategies. Registration unlocks every volume in the series.
The structural fine print
The favorable treatment typically requires bearing unlimited liability during the drilling phase through a general-partner-style interest — a real legal exposure that most programs convert to limited-partner status after drilling, but which deserves counsel’s eyes beforehand. Alternative minimum tax considerations, recapture on early disposition, and state-level treatment all vary with circumstances and current law. And the sponsor question towers over everything: operator track record — actual well results across prior programs, not projected type curves — is the diligence.
Who this actually fits
IDC programs make the most sense for investors with substantial current ordinary income, genuine risk capital they can afford to lose entirely, and the patience for a multi-year, illiquid, commodity-linked hold — as a small, deliberate slice of a broader plan designed with their CPA. For anyone else, there are gentler tools in the drawer.
See current 1031 & DST offerings
Verified accredited investors can request access to our private investor portal to review institutionally vetted offerings.
If a drilling program is in front of you, we’ll give you the honest read — the operator’s record, the fee load, the liability mechanics, and whether the strategy fits your tax picture or just decorates it.
Ben Carmona is the President & CEO of Carmona Wealth. With more than 20 years of applied experience, Ben is an expert in 1031 exchanges, Delaware Statutory Trusts, real estate investments, structures, and strategies.… Full profile →
Talk It Through With Our Team
Private, no-obligation, and specific to your numbers — not a sales script.
Continue reading
Ready to Go Deeper?
Request access to the private investor portal to see current offerings, or schedule a consultation to map your options.